Overview of the Artificial Intelligence (AI) In Higher Education Market
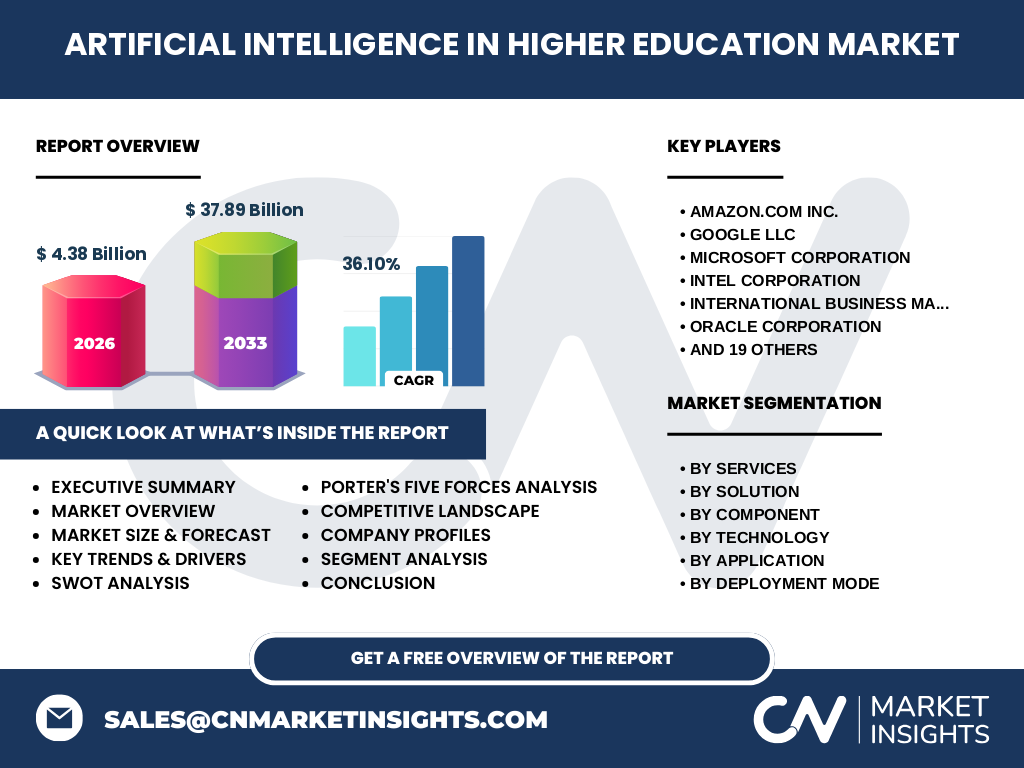
The Artificial Intelligence (AI) In Higher Education Market encompasses the integration of advanced algorithmic solutions within academic environments. Currently valued at 4.38 Billion in 2026, the industry serves as a foundational pillar for digital transformation, enabling personalized learning and administrative efficiency across global institutions. Our analysis defines this sector by the intersection of pedagogical software and enterprise-level data processing.
Structural Growth Drivers and Market Restraints
Growth is propelled by the necessity for data-driven decision-making, while the 36.10% CAGR underscores the massive demand for automation. Key restraints include stringent data privacy regulations, such as GDPR and FERPA, which complicate the deployment of AI-powered LMS. Despite these hurdles, the opportunity to scale Intelligent Tutoring Systems allows institutions to overcome instructor shortages and bridge the learning gap effectively.
Emerging Trends Shaping Academic Technology
A pivot toward Generative AI and Natural Language Processing (NLP) is transforming how Chatbots for Student Support function. Our research highlights a trend where institutions are moving away from monolithic platforms toward modular, cloud-based architectures. This hyper-personalized approach to curriculum delivery is becoming the standard, as companies like Knewton Inc. and Cognii Inc. refine adaptive technologies to improve long-term student retention.
COVID-19 Impact and Recovery Trajectory
The pandemic served as a catalyst for digital adoption, forcing a rapid transition to remote instruction. While initially reactive, the recovery trajectory is now highly strategic. The industry has shifted from emergency continuity to permanent infrastructure investment, focusing on Cloud-Based deployment modes. This transition ensures that the gains made in virtual facilitation during 2020 are now solidified as core Artificial Intelligence (AI) In Higher Education Market operations.
Competitive Benchmarking and Market Concentration
The landscape is a mix of hyperscalers like Microsoft Corporation and Google LLC, alongside specialized EdTech innovators like Instructure Holdings Inc. and D2L Inc. Concentration is moderate, as major players focus on AI-Powered Learning Management Systems (LMS), while niche startups disrupt specific areas like Predictive Analytics Tools. Strategic partnerships remain the primary driver for achieving competitive dominance in an increasingly fragmented market.
Executive Summary of Global Market Projections
Our analysis indicates that the Artificial Intelligence (AI) In Higher Education Market is poised for explosive growth, with a valuation expected to reach 37.89 Billion by 2033. This trajectory reflects a massive migration toward integrated technological ecosystems. The convergence of Machine Learning (ML) and administrative workflows signifies a maturation of the sector, shifting from experimental pilot programs to mission-critical infrastructure for universities worldwide.
Forecast Analysis (2027 to 2033)
The forecast period from 2027 to 2033 reveals a consistent 36.10% CAGR, driven by the democratization of AI access. We anticipate that Data Analytics and Reporting Services will see the highest demand as institutions prioritize measurable student outcomes. By 2033, the market will likely reach 37.89 Billion, bolstered by widespread adoption in both public and private higher education sectors globally.
Segmentation Analysis: Solutions and Services
Segmentation is categorized by Solution—including AI-Driven Assessment Tools and Smart Content—and Services like Maintenance and Upgradation. Each segment plays a vital role in operational continuity. While solutions provide the core intellectual property for learning, services ensure the seamless integration and ethical governance required by modern academic frameworks. Our data confirms that Implementation Services represent a significant revenue stream for tier-one vendors.
Regional Market Performance Distribution
North America remains the dominant revenue generator due to the concentration of top-tier research universities and tech giants like Amazon.com Inc. and Oracle Corporation. Meanwhile, the Asia-Pacific region is experiencing the fastest growth, fueled by government initiatives to modernize education infrastructure. Europe follows, with strict regulatory compliance shaping the adoption of Computer Vision and other sophisticated, high-compliance AI applications in the classroom.
In-Depth Regional Review
In North America, the market focuses on Personalized Learning Platforms to address rising tuition costs and student performance. In contrast, Latin America and Asia-Pacific emphasize Cloud-Based Intelligent Tutoring Systems to overcome physical logistical hurdles and instructor scarcity. These localized market constraints force vendors to customize their delivery models to ensure regional compatibility, influencing the overall Artificial Intelligence (AI) In Higher Education Market growth strategy.
Strategic Positioning of Leading Companies
Market leaders utilize distinct strategic pillars: Pearson Plc and John Wiley and Sons Inc. leverage deep content expertise to drive Curriculum Development Tools. Conversely, Cognizant Technology Solutions India Private Limited and IBM focus on enterprise-grade infrastructure. Meanwhile, Coursera Inc. and 2U Inc. prioritize platform scalability, positioning themselves as essential partners for digital transformation rather than mere software vendors.
Porter's Five Forces Analysis
The threat of new entrants is high due to rapid innovation in Machine Learning, but balanced by the high barriers to entry in institutional procurement processes. Bargaining power of buyers is significant, as universities demand long-term scalability. Competitive rivalry is intense, forcing incumbents like Adobe Inc. and Intel Corporation to innovate constantly, while the threat of substitutes remains low given the unique pedagogical benefits AI provides.
SWOT Analysis of the Industry
Strengths include the scalability of Cloud-Based deployments. Weaknesses lie in the complexity of data interoperability between legacy LMS and modern AI. Opportunities reside in the untapped potential of Predictive Analytics Tools for student retention. Threats center on evolving regulatory bodies and the potential for algorithmic bias, which requires companies to invest heavily in ethical, transparent AI frameworks to maintain institutional trust.
Value Chain Analysis
The value chain starts with data architects and algorithm developers, followed by integration partners like Kaltura Inc. or Jenzabar Inc.. The flow moves from raw computational inputs to value-added service layers like Consulting Services and Training. Ultimately, this value reaches the end-user—students and faculty—enabling improved learning outcomes. This structured flow ensures that technical innovation is effectively translated into tangible educational utility.
Investment Insights and Recommendations
We identify Data Analytics and Reporting Services as the highest potential investment area, as universities prioritize ROI-focused metrics. Investors should favor companies providing interoperable solutions that integrate easily with existing LMS. With a 36.10% CAGR, focus areas should include firms with proprietary NLP capabilities, as these provide a defensible 'moat' in the evolving Artificial Intelligence (AI) In Higher Education Market landscape.
Conclusion and Key Takeaways
The Artificial Intelligence (AI) In Higher Education Market is transitioning from an auxiliary benefit to a mandatory core competency. With a forecast value of 37.89 Billion by 2033, stakeholders must prioritize ethical AI adoption, interoperability, and student-centered outcomes. Success will reward firms that seamlessly integrate advanced Predictive Analytics and personalized learning into the existing academic fabric.
Research Methodology and Baseline Estimates
Our methodology employs triangulation: we combine trade registry data from key innovators, primary interviews with Chief Information Officers, and macroeconomic indicators from global education ministries. We cross-reference vendor revenue reports, such as those from BridgeU Ltd. and Querium Corporation, against internal bottom-up market sizing models to ensure the 4.38 Billion baseline for 2026 accurately reflects current market saturation and growth potential.
Scope of the Report
This report covers the Artificial Intelligence (AI) In Higher Education Market from 2026 to 2033, analyzing solution types, deployment modes, and geographic regions. Limitations include the rapid pace of regulatory changes and localized pedagogical shifts. We strictly focus on higher education applications, excluding K-12 and corporate training segments to ensure deep, actionable insights for stakeholders invested in the university ecosystem.
Recent Developments in the Sector
Recent strategic moves include major product launches in Generative AI-enabled tutoring, alongside partnerships between technology innovators like Brainly Inc. and legacy academic publishers. The industry has seen a surge in M&A activity as larger players seek to acquire specialized Computer Vision and Predictive Analytics capabilities. These developments signal a tightening of the market, where consolidation is becoming a strategy for capturing the 37.89 Billion future market share.